Quick Answer
A Florida portfolio loan is a mortgage that a financial institution keeps in its own investment portfolio rather than selling through the standard secondary market. Because the institution retains the mortgage risk, it may offer qualification guidelines that differ from conventional programs.
A Florida portfolio loan can be useful when your finances or property don’t fit neatly into standard mortgage guidelines. Portfolio financing isn’t 1 specific program with universal rules. Instead, it describes mortgages that are kept by the financial institution, which can create additional flexibility for certain borrowers.
A Personal Story
Awhile back I was working with a Florida business owner who had strong cash flow, excellent savings, and a successful company, but his tax returns showed much less income because of legitimate business deductions. On paper, his financial profile looked weaker than his actual situation. A standard mortgage structure wasn’t giving us an accurate picture of his ability to make the payment.
That’s a situation where I look beyond the obvious program first. My advice is to identify why the standard qualification isn’t working. Sometimes bank statements, assets, property income, or a portfolio structure can provide a more realistic way to evaluate financial strength.
What Is A Florida Portfolio Loan?
A Florida portfolio loan is a mortgage that the financial institution intends to keep on its own books rather than immediately selling into the standard secondary mortgage market.
Many conventional mortgages are structured to meet guidelines that allow them to be purchased by Fannie Mae or Freddie Mac. Those guidelines create consistency across the mortgage market.
A portfolio mortgage works differently. Because the financial institution retains the mortgage and the associated risk, it can sometimes use its own qualification standards while still complying with applicable mortgage laws.
That flexibility can involve factors such as:
- Income documentation
- Credit history
- Debt ratios
- Cash reserves
- Property type
- Loan amount
- Investment-property ownership
- Assets and liquidity
Portfolio doesn’t automatically mean easier approval. In some cases, the requirements can actually be stricter because the financial institution is keeping the risk rather than transferring it elsewhere.
It’s also important not to confuse “portfolio” with “Non-QM.” Some portfolio mortgages are Non-QM, but the terms aren’t interchangeable. A portfolio mortgage describes what happens to the mortgage after it’s originated, while Non-QM describes a mortgage that falls outside certain Qualified Mortgage standards.
The Doce Mortgage Group offers several Florida Non-QM financing options that can address situations involving bank statements, assets, rental income, and other nontraditional qualification methods.
Who Might Qualify For A Portfolio Loan In Florida?
Borrowers with strong overall finances but unusual income, property, or mortgage characteristics may be good candidates for portfolio financing.
Common situations can include:
- Self-employed business owners
- High-net-worth borrowers
- Retirees with substantial assets
- Buyers with irregular income
- Real estate investors
- Borrowers owning numerous properties
- Buyers needing very large mortgages
- Certain unusual property situations
- Borrowers with complex tax returns
For example, a self-employed borrower may earn substantial cash flow while reporting considerably less taxable income after business deductions. Depending on the available program, bank deposits could provide a better picture of earnings than tax returns alone.
The Doce Mortgage Group currently offers bank statement financing for self-employed Florida borrowers using 12 or 24 months of qualifying bank statements rather than relying solely on traditional tax-return income.
High-net-worth buyers can present the opposite problem. Someone may have $2,000,000 in investments but relatively little employment income. In those situations, asset-based qualification or another customized structure may be more appropriate. That’s why customized financing for high-net-worth Florida buyers can be valuable when wealth doesn’t appear primarily on a paycheck.
Where Portfolio Flexibility May Be Most Useful
| Borrower Or Property Situation | Standard Financing Fit | Portfolio Flexibility |
|---|---|---|
| Stable W-2 income | Excellent fit | Usually less necessary |
| Complex self-employed income | Limited fit | Strong flexibility |
| Strong assets, low taxable income | Difficult fit | Excellent flexibility |
| Unusual property | Limited fit | Strong flexibility |
| Large jumbo mortgage | Moderate fit | Excellent flexibility |
This is a general comparison, not an approval chart. Actual requirements vary considerably between portfolio programs.
How Is A Portfolio Loan Different From A Conventional Mortgage?
The biggest difference is that conventional mortgages generally follow standardized secondary-market guidelines, while portfolio financing may allow more customized qualification.
For 2026, the FHFA baseline conforming loan limit is $832,750 for a 1-unit property in most of the country. Mortgages above the applicable conforming limit enter the jumbo market, where portfolio structures are more common, although not every jumbo mortgage is a portfolio mortgage.
Portfolio financing can also matter well below jumbo prices. Florida Realtors reported that the statewide single-family median sale price reached $425,000 in Q2 2026. The reason someone chooses portfolio financing may have nothing to do with an expensive home. The real issue could be business income, substantial assets, multiple investment properties, or another characteristic that doesn’t fit standard guidelines.
I prefer to compare the standard option first. If it works well, there may be no reason to choose a more specialized structure. When it doesn’t, portfolio financing gives us another set of possibilities to evaluate.
You can begin through our secure application portal so we can review your income, assets, credit, property, and overall scenario before deciding which type of financing makes the most sense.
What Income Documentation Can Work With A Portfolio Loan?
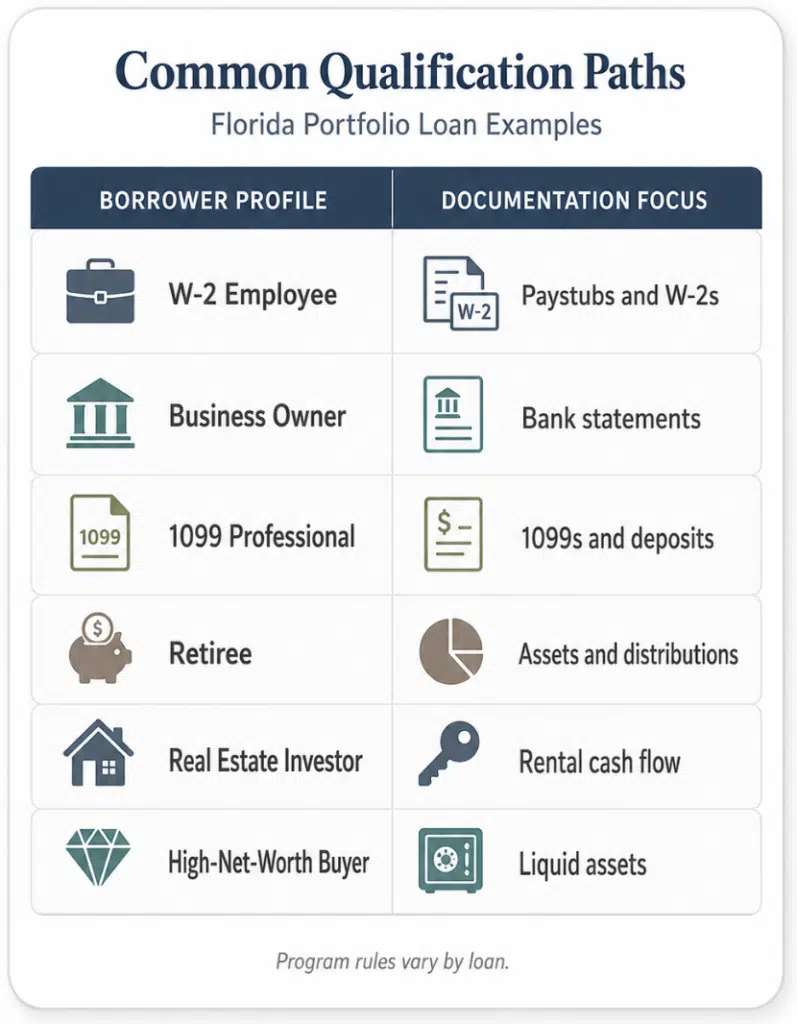
Portfolio financing may allow income to be evaluated in ways that differ from a standard W-2 and tax-return approach.
The exact documentation depends on the program, but possible methods can include:
- W-2 income
- Tax returns
- Bank statements
- 1099 income
- Profit and loss statements
- Investment distributions
- Retirement income
- Trust income
- Asset depletion
- Rental-property cash flow
This flexibility can matter for Florida business owners whose taxable income is reduced by legitimate deductions. Someone might have strong business deposits and substantial liquidity while showing relatively modest taxable income on a return.
That doesn’t mean income can simply be ignored. The CFPB’s Ability-to-Repay rules generally require a reasonable, good-faith determination that a consumer can repay a residential mortgage when the rule applies.
The difference is how financial strength may be documented.
For example, The Doce Mortgage Group offers asset-based mortgage options that can use qualifying liquid assets rather than relying entirely on employment income. Another option may involve buying a Florida home without traditional income verification when the borrower has enough assets and meets the specific program requirements.
I’ve found that the most important step is identifying where the borrower’s financial strength actually comes from. For one person, it’s business cash flow. For another, it might be investments, rental properties, retirement accounts, or a combination of several sources.
What Credit, Down Payment, And Reserves Might Be Required?
Requirements vary widely because portfolio mortgages don’t follow 1 universal set of qualification rules.
A flexible income method doesn’t necessarily mean flexible requirements everywhere else. In fact, some programs may offset unusual income documentation by asking for stronger credit, more equity, or larger cash reserves.
Factors commonly reviewed include:
- Credit score
- Recent payment history
- Down payment
- Loan-to-value ratio
- Cash reserves after closing
- Mortgage amount
- Property type
- Occupancy
- Number of financed properties
- Recent credit events
A borrower with excellent liquidity but irregular income may be viewed very differently from someone with limited reserves and recent late payments.
Down payment expectations can also differ substantially. Some specialized options may require 20% or more, while certain jumbo portfolio structures may allow less for highly qualified borrowers.
The Mortgage Bankers Association reported that overall mortgage credit availability increased 2.5% in July 2026, while its Jumbo Mortgage Credit Availability Index increased 4.2%. That doesn’t mean every borrower will qualify more easily, but it does show that available mortgage products can expand or contract as market conditions change.
How Different Strengths Can Offset Complexity
| Financial Factor | Standard Profile | Portfolio Profile May Emphasize |
|---|---|---|
| Traditional income | Very important | Moderately important |
| Liquid assets | Important | Very important |
| Cash reserves | Important | Very important |
| Property strength | Important | Highly important |
| Flexible documentation | Limited flexibility | High flexibility |
This is a general illustration only. Every portfolio program sets its own requirements.
How Does A Portfolio Loan Compare With Non-QM, DSCR, And Asset-Based Financing?
These terms can overlap, but they describe different things and shouldn’t be treated as interchangeable.
A portfolio mortgage describes a mortgage being retained rather than sold through the usual secondary-market channel. Non-QM refers to financing that falls outside certain Qualified Mortgage standards. DSCR financing focuses primarily on rental-property cash flow, while asset-based financing may qualify a borrower using available wealth.
| Financing Type | Main Qualification Focus | Common Use |
| Portfolio | Customized overall profile | Complex borrower or property |
| Non-QM | Alternative documentation | Self-employed or irregular income |
| DSCR | Property rental cash flow | Investment properties |
| Asset-Based | Liquid assets | Retirees and high-net-worth buyers |
| Conventional | Standardized guidelines | Traditional income profiles |
An investor who owns several Florida rentals might not need a general portfolio mortgage if a Florida DSCR program solves the qualification issue directly. A wealthy retiree may be better served by asset-based financing. A business owner could fit a bank-statement program.
That’s why I don’t start by trying to force someone into a portfolio loan. I start with the problem we’re trying to solve, then compare the structures that address it with the least unnecessary cost and complexity.
Portfolio and alternative financing can also carry different rates, points, down payment requirements, and reserve expectations. You can compare how different rates, loan amounts, and down payments affect your estimated monthly cost using our Florida Mortgage Payment Calculator.
The best Florida portfolio loan is usually the one that solves a specific qualification problem without creating new financial problems somewhere else.
When Does A Florida Portfolio Loan Make Sense?
A Florida portfolio loan can make sense when your overall financial strength is solid, but standard mortgage guidelines don’t accurately reflect your situation.
Common examples include:
- Complex self-employed income
- Large investment portfolios
- Significant liquid assets
- Multiple rental properties
- Irregular income
- Large mortgage amounts
- Unique property characteristics
- Recent business growth
- Complicated tax returns
For example, an investor who owns several rental properties may have strong cash flow but a financial profile that becomes difficult to document under a standard mortgage structure. A portfolio option may allow the entire picture to receive more consideration.
The same can be true for a business owner whose tax returns include large deductions, or a retiree whose wealth comes primarily from investments rather than employment.
I usually look for a specific reason to use portfolio financing. If conventional financing works well, there may be little benefit to choosing something more specialized.
When Portfolio Financing May Be Worth Exploring
| Situation | Portfolio Fit |
|---|---|
| Standard W-2 income and strong credit | Low |
| Complex self-employed income | High |
| Large liquid investment portfolio | High |
| Numerous rental properties | High |
| Irregular but documented income | High |
| Standard property and simple finances | Low |
| Unusual property characteristics | Moderate to High |
| Jumbo financing needs | Moderate to High |
This chart is general guidance only. Individual portfolio programs can have very different qualification rules.
When Might Another Mortgage Be Better?
Another mortgage may be better when your financial profile fits a more standardized program with lower costs or simpler terms.
Portfolio financing isn’t automatically superior because it offers flexibility.
Someone buying a typical primary residence with stable W-2 income, strong credit, and enough down payment may find that conventional financing provides a simpler and potentially less expensive solution.
An investor purchasing a stabilized rental may find that DSCR financing directly addresses the qualification problem. A self-employed borrower may fit a bank-statement program without needing a broader portfolio structure.
If you’re considering buying an investment property in Florida, its a good idea to compare financing choices in the context of actual cash flow, insurance, taxes, reserves, and maintenance.
Pros And Cons
Pros:
- Flexible qualification methods
- Helpful for complex income
- May accommodate significant assets
- Can work for unusual properties
- Useful for some jumbo borrowers
- May help investors with multiple properties
- More room for customized underwriting
Cons:
- Rates may be higher
- Larger down payments may be required
- Reserve requirements can be substantial
- Guidelines vary between programs
- Fees may be higher
- Fewer standardized protections and comparisons
- Refinancing options should be considered carefully
I recommend comparing the total cost, not simply whether a portfolio mortgage gets approved. Flexibility has value, but it should solve a real problem.
Myths Vs Facts
Myth: Portfolio mortgages are only for borrowers with bad credit
Fact: Many portfolio borrowers have strong credit and substantial assets but complicated income or property situations.
Myth: A portfolio mortgage is the same as a Non-QM mortgage
Fact: The terms can overlap, but they describe different characteristics of a mortgage.
Myth: Portfolio financing always requires a huge down payment
Fact: Down payment requirements vary according to the program, property, credit profile, and overall transaction.
Myth: Portfolio mortgages don’t verify ability to repay
Fact: Applicable federal rules still require appropriate evaluation of a borrower’s ability to repay in covered transactions.
The CFPB discusses how ability to repay and qualified mortgage requirements help ensure that a borrower’s income, assets, debts, and overall financial profile are properly evaluated before approval.
Myth: Portfolio financing is automatically more expensive
Fact: Pricing varies, so the correct comparison should include rate, points, fees, down payment, reserves, and long-term plans.
Common Mistakes
Common mistakes include:
- Assuming portfolio means easy approval
- Comparing only interest rates
- Ignoring upfront points and fees
- Underestimating reserve requirements
- Failing to document available assets
- Mixing business and personal funds
- Waiting too long to organize bank statements
- Assuming every unusual property qualifies
- Choosing portfolio financing unnecessarily
- Ignoring future refinance options
- Misunderstanding adjustable-rate terms
- Failing to compare alternatives
One mistake I see is focusing so heavily on getting approved that the borrower forgets to ask whether the structure still makes financial sense 3 or 5 years later.
Key Facts
- Portfolio mortgages are kept in-house
- Guidelines can be more customized
- Requirements vary between programs
- Self-employed borrowers may benefit
- Significant assets can support qualification
- Investment-property owners may have additional options
- Portfolio and Non-QM aren’t identical
- Down payments can vary widely
- Cash reserves may be important
- Rates and fees should be compared carefully
- Standard financing may still be the better option
- Property type can affect eligibility
People Also Ask
Are portfolio mortgage rates higher?
They can be, but pricing varies according to risk, documentation, loan amount, property type, down payment, reserves, and market conditions.
Are portfolio loans harder to qualify for?
Not necessarily. They may be more flexible in one area while requiring stronger assets, reserves, equity, or credit elsewhere.
Can I get a portfolio loan after a recent credit problem?
Possibly, depending on the program and the overall strength of the transaction. Recent credit events can still affect eligibility, pricing, down payment, and reserve requirements.
How Can We Help You Find The Right Florida Mortgage?
We can look at your complete financial picture and determine whether a Florida portfolio loan actually provides an advantage or whether conventional, jumbo, Non-QM, bank-statement, asset-based, DSCR, or another option fits better.
Our goal is to solve the qualification problem without adding unnecessary cost or complexity. You can request a free quote so we can compare available options around your income, assets, credit, property, and long-term plans.
You can also review our customer reviews to see what borrowers have said about working with our team. We’re proud that The Doce Mortgage Group recently received the prestigious WalletHub Award and was recognized as one of the best mortgage brokers in several cities throughout Florida.
When you’re ready to find out whether a Florida portfolio loan fits your situation, you can Get Started Now, or connect with a loan officer live at 305-661-3434.