Quick Answer
For many dentists, a specialized doctor loan can be a strong option because it may offer 0% down, no PMI, flexible student loan treatment, and qualification using a future employment contract. Conventional and jumbo financing can still be better in some situations, so the right choice depends on your income, debt, savings, career stage, and home price.
Dentists often have financial profiles that don’t fit neatly into a standard mortgage box. You may earn a strong income while carrying substantial dental school debt, transitioning into an associate position, buying into a practice, or building savings after years of training. A Florida dentist mortgage loan can address some of those challenges while still giving you access to higher-priced homes throughout the state.
A Personal Story
I worked with a medical professional whose income looked excellent on paper, but the timing of a new position and a large student loan balance made the mortgage decision more complicated than expected. The question wasn’t whether this person could afford a home. It was which mortgage structure recognized the financial reality of an early-career professional.
I approach dentist financing the same way. I want to know where you are in your career, what your student loan payment actually is, how much cash you want to preserve, and whether your income is changing. Those details can matter more than simply comparing advertised rates.
What is a Florida Dentist Mortgage Loan?
A Florida dentist mortgage loan is a specialized doctor mortgage available to qualifying dental professionals, including DDS and DMD borrowers.
The Doce Mortgage Group’s current Florida Doctor Loan program specifically includes Doctors of Dental Surgery and Doctors of Dental Medicine among eligible medical professionals. Qualifying borrowers may have access to financing up to $2,000,000 with 0% down and up to $3,000,000 with 10% down, depending on the complete financial profile and program requirements.
Another major difference is private mortgage insurance. Qualifying doctor loan programs can eliminate PMI even when the dentist puts less than 20% down.
That can be significant for a dentist who has a high income but would rather keep $100,000 or $200,000 available for emergency reserves, investments, relocation costs, or future practice-related expenses instead of putting the money entirely into a home.
Florida’s housing market makes that flexibility especially relevant. According to Florida Realtors’ July 2026 housing market data, the statewide median price for an existing single-family home was $425,000. Dentists shopping in Boca Raton, Miami, Fort Lauderdale, Palm Beach, Naples, Tampa, or desirable Orlando communities may encounter prices far above that statewide median.
How is a Dentist Loan Different From a Conventional Mortgage Loan?
A dentist loan can account for student debt, career timing, and limited early-career savings in ways that conventional financing may not.
Dental school can create an unusual situation. A dentist may have excellent long-term earning potential while carrying a large educational debt balance. A new dentist might also sign an employment agreement months before receiving the first paycheck.
Certain doctor loan programs can use a documented income-driven student loan payment rather than relying only on the total outstanding balance. Qualifying borrowers may also be able to use a fully executed future employment contract when the new position begins within the program’s allowed timeframe.
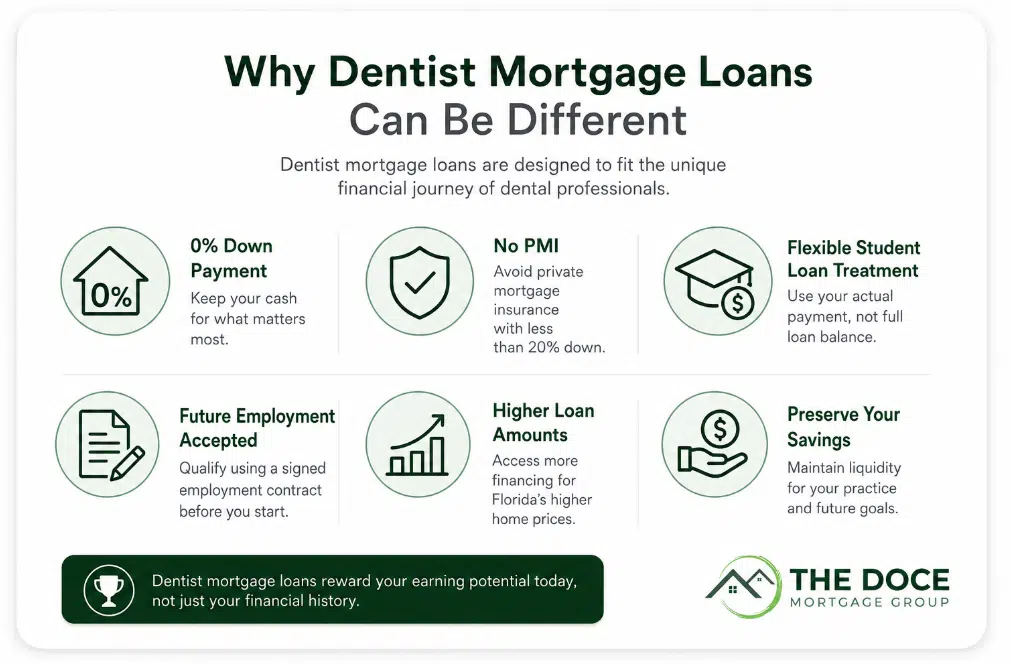
Doctor loans can help Florida medical professionals buy a home with little or no down payment. These differences can become especially valuable early in a medical career.
Where A Dentist Mortgage Can Have An Advantage
| Dentist Situation | Specialized Dentist Loan | Conventional Financing |
|---|---|---|
| Large dental school debt | More flexible treatment possible | Standard debt calculation |
| Limited down payment savings | Potentially strong fit | More cash may be needed |
| New employment contract | May allow future income | More restrictive |
| Less than 20% down | No PMI on qualifying programs | PMI may apply |
| Higher-priced Florida home | Options into jumbo range | May require jumbo financing |
| Established income and 20% down | Compare both | Often very competitive |
This is a general comparison, not an approval chart. Actual terms depend on credit, income, assets, employment, property type, and the specific program.
Who Can Qualify for a Dentist Mortgage Loan in Florida?
DDS and DMD professionals may qualify, including dentists at different stages of their careers, provided they meet the requirements of the specific program.
That can include an associate dentist joining an established practice, a dentist relocating to Florida, or an experienced dental professional purchasing a higher-priced primary residence.
Having a dental degree doesn’t automatically guarantee approval. Credit history, income, assets, employment documentation, purchase price, property type, and other debts still matter.
One thing I encourage dentists to do is determine their realistic buying range before becoming attached to a property. You can use our Home Affordability Calculator to test your income, debts, down payment, Florida insurance, taxes, and HOA costs before you start comparing specific homes.
How Much Can a Florida Dentist Borrow?
The amount a dentist can borrow depends on income, credit, debts, available assets, down payment, property type, and the specific mortgage program.
Specialized dentist financing can reach well beyond the normal conforming mortgage range. The Doce Mortgage Group currently offers qualifying medical professionals up to $2,000,000 with 0% down and financing up to $3,000,000 with 10% down through certain doctor loan programs.
That can matter in Florida markets where higher-priced homes are common. Under FHFA’s 2026 conforming loan limits, the baseline limit for a 1-unit property is $832,750. The maximum limit in qualifying high-cost areas is $1,249,125.
A dentist purchasing a $1,500,000 home in Boca Raton, Naples, Miami, Palm Beach, or another expensive Florida market may therefore need to consider doctor or jumbo financing rather than a standard conforming mortgage.
I don’t recommend choosing a maximum purchase price simply because you qualify for it. Dentists can have high incomes, but they may also be funding retirement accounts, paying student debt, buying into a practice, purchasing equipment, or building business reserves.
How Purchase Price Can Change The Financing Conversation
| Florida Home Price | Financing Worth Comparing | Main Consideration |
|---|---|---|
| $500,000 | Doctor and conventional | Down payment and PMI |
| $850,000 | Doctor and conventional | Conforming limit |
| $1,250,000 | Doctor and jumbo | Cash requirements |
| $1,750,000 | Doctor and jumbo | Liquidity and reserves |
| $2,500,000 | Doctor and jumbo | Down payment and overall cost |
This is a general comparison only. Actual options depend on the borrower, property, location, and current program requirements.
How Are Dental School Loans Treated?
Student debt may receive more flexible treatment with a dentist mortgage than with some standard mortgage programs.
A dentist can graduate with a large student loan balance while already having excellent earning potential. Looking only at the total balance can give an incomplete picture of that person’s ability to manage a mortgage.
Certain doctor loan programs can use the dentist’s documented income-driven student loan payment when calculating debt obligations. That can produce a significantly different result than using a hypothetical payment based primarily on the outstanding balance.
For example, consider 2 dentists who each owe $250,000 in student loans:
Why The Student Loan Calculation Matters
| Borrower | Student Loan Balance | Qualifying Payment Used | Potential Effect |
|---|---|---|---|
| Dentist A | $250,000 | Lower documented payment | More buying power possible |
| Dentist B | $250,000 | Higher calculated payment | Less buying power possible |
The important number isn’t simply “$250,000.” It’s the monthly obligation that the particular mortgage program requires us to use.
I’ve found this is one of the most misunderstood parts of dentist financing. A borrower can have substantial educational debt and still be in a strong financial position because income, career stability, savings, and the actual required payment all matter.
Can a Dentist Qualify Before Starting a New Job?
Yes, certain doctor mortgage programs can allow an eligible dentist to qualify using a signed future employment contract.
This can be particularly valuable when relocating to Florida. A dentist might accept an associate position with a dental group in Tampa, Orlando, Jacksonville, Fort Lauderdale, or South Florida, then want to purchase a home before the first day of work.
Some specialized programs can evaluate a fully executed employment agreement showing the future salary and start date, subject to the program’s timing and documentation requirements.
That means a dentist doesn’t necessarily have to rent for several months simply to establish a paycheck history.
This same flexibility becomes especially useful at higher purchase prices. Medical professionals in Florida that are considering a jumbo doctor loan should consider how employment contracts, student debt, and limited early-career savings can intersect.
When I’m working with someone who’s relocating, I want to review the employment contract before the home search becomes serious. It gives us time to identify any conditions that could affect the closing date.
What if You Own a Dental Practice?
Practice ownership can create additional mortgage options, but it can also make income documentation more complicated.
A dentist who owns a practice may receive income through salary, distributions, business profits, or several different sources. Business deductions can also reduce taxable income even when the practice generates healthy cash flow.
A conventional mortgage may still work perfectly well for an established practice owner. In other situations, doctor financing, bank statement financing, or another Non-QM structure may deserve consideration.
The goal isn’t to force every dentist into the same product. I want to identify the income that can actually be documented, how much cash should remain available after closing, and which mortgage gives the dentist the strongest overall financial position.
If you already have a property or price range in mind, you can use our secure mortgage application so we can compare the available financing using your actual income, student debt, assets, employment, and purchase plans.
Pros and Cons
A Florida dentist mortgage loan can offer major advantages, but it isn’t automatically the best choice for every dentist.
Dentist loan advantages include:
- Potential 0% down financing
- No PMI on qualifying programs
- Flexible student loan treatment
- Future employment contract options
- Access to higher loan amounts
- Ability to preserve liquid savings
Potential disadvantages include:
- Eligibility is limited to qualifying professionals
- Rates may differ from conventional financing
- Programs can have specific property requirements
- Primary residence requirements may apply
- Less money down means more borrowed
For an established dentist with strong savings and little educational debt, conventional or jumbo financing may sometimes produce a better overall cost.
When Might Conventional or Jumbo Financing Be Better?
Conventional or jumbo financing may be better when a dentist has established income, substantial cash reserves, and little need for specialized qualification flexibility.
Suppose a practice owner can comfortably put 20% down while still maintaining significant savings. Conventional financing could eliminate PMI anyway, and the dentist may receive more attractive pricing.
The same applies at higher purchase prices. A wealthy practice owner might benefit from comparing a doctor loan with jumbo financing or customized mortgage solutions for high-net-worth borrowers.
Interest rates should be part of the comparison, but not the entire decision. For market context, Freddie Mac’s Primary Mortgage Market Survey reported an average 30-year fixed conventional rate of 6.65% on August 20, 2026. Your actual rate can differ significantly based on credit, loan size, property, down payment, and program.
Which Financing Profile Deserves a Closer Look?
| Dentist Profile | Option Worth Comparing First |
|---|---|
| New associate with limited savings | Dentist loan |
| Dentist with large student debt | Dentist loan |
| Relocating with future contract | Dentist loan |
| Established owner with 20% down | Conventional |
| Buying a luxury Florida home | Doctor loan or jumbo |
| High assets but complex income | Multiple options |
| Unsure which costs less | Compare both |
This chart is a starting point only. Actual financing should be compared using the same purchase price, down payment, loan term, and property assumptions.
Myths Vs Facts
Myth: Every dentist should use a doctor mortgage
Fact: Conventional or jumbo financing may be better for some established dentists
Myth: You need 20% down to avoid PMI
Fact: Qualifying dentist mortgage programs can eliminate PMI with much less down
Myth: Large dental school debt prevents homeownership
Fact: The qualifying impact depends partly on how the required monthly payment is calculated
Myth: 0% down means no money is needed at closing
Fact: Closing costs, prepaid expenses, insurance, and reserves may still be required
Common Mistakes
One of the biggest mistakes is choosing a mortgage solely because it requires the smallest down payment.
Other mistakes include:
- Comparing only interest rates
- Ignoring the value of cash reserves
- Assuming student debt prevents qualification
- Waiting too long to review employment contracts
- Buying at the maximum approved amount
- Forgetting Florida insurance costs
- Ignoring HOA expenses
- Comparing mortgages using different assumptions
- Assuming every doctor program works identically
I also encourage dentists to think beyond today’s payment. Someone opening or purchasing a practice may value liquidity very differently from an established dentist with substantial investment assets.
Key Facts
- DDS and DMD borrowers may qualify
- Some programs offer 0% down
- Qualifying programs may eliminate PMI
- Student debt treatment can differ
- Future employment contracts may be accepted
- Loan amounts can extend into jumbo territory
- Conventional financing may still be cheaper
- Practice ownership can complicate income documentation
- Florida insurance affects total housing costs
- Cash preservation can be valuable early in a career
People Also Ask
Are dentist mortgage rates higher than conventional mortgage rates?
Sometimes. Pricing varies, which is why dentists should compare rate, PMI, down payment, loan balance, and cash remaining after closing.
Can a self-employed dentist qualify for a doctor loan?
Potentially. Practice owners may qualify depending on how income, business ownership, assets, debts, and other factors are documented.
Can I refinance a dentist mortgage later?
Yes, refinancing may be possible if your financial profile, equity, rates, or long-term goals change.
How Can We Help You Find the Right Dentist Mortgage?
We can compare doctor, conventional, jumbo, bank statement, and other mortgage options based on your actual career stage, dental school debt, income, employment contract, practice ownership, available assets, and Florida home purchase.
Our goal isn’t to assume a dentist mortgage is automatically best. We want to identify which structure gives you the right balance of monthly cost, upfront cash, flexibility, and long-term value. You can review our customer reviews to see what borrowers say about working with our team.
We’re also proud that The Doce Mortgage Group recently received the prestigious WalletHub Award and was recognized as one of the best mortgage brokers in several cities throughout Florida.
If you’re considering a Florida dentist mortgage loan, we can compare the available options around your actual numbers, and when you’re ready, you can Get Started Now, or connect with a loan officer live at 305-661-3434.