Quick Answer
VA Mortgage Pre Approval can still be possible when your finances don’t fit a simple W-2 profile. The review considers VA eligibility, usable income, credit, debts, residual income, assets, occupancy, and the details behind unusual financial circumstances.
Veterans often assume that self-employment, variable income, a recent job change, high debt, or past credit trouble will prevent them from using their VA benefit. That isn’t necessarily true. VA preapproval can evaluate the complete financial picture, which matters when your situation needs more explanation than a standard paycheck and credit score.
Alex’s Professional Insights
I worked with a veteran whose income looked complicated because he had recently moved from military service into civilian work while also earning income from a small business. He assumed the mixed income history would end the conversation. Once I separated the income sources and documented what was stable, the situation became much clearer.
My advice is to bring unusual circumstances up early. Don’t try to make a complicated file look simple. A strong VA Mortgage Pre Approval comes from identifying the questions before you’re under contract and documenting the answers clearly.
What Does VA Mortgage Pre Approval Actually Mean?
VA Mortgage Pre Approval is a review of your eligibility and finances that estimates whether you’re likely to qualify and how much you may be able to finance before making an offer.
A thorough review may examine documents supporting your income, debts, assets, credit history, housing costs, and VA eligibility. Preapproval still isn’t final approval. The property must qualify, your finances can be rechecked, and the final file must satisfy applicable requirements.
The VA advises buyers to review their credit profile, income, expenses, and monthly budget before shopping for a home. Veterans Affairs
The Doce Mortgage Group offers dedicated Florida VA loans for eligible veterans, active-duty service members, and qualifying surviving spouses. You can also explore possible purchase scenarios using our VA Loan Calculator. The Doce Mortgage Group
VA Preapproval Review Chart
| Eligibility | █████ | Service history and entitlement |
| Income | █████ | Stability and continuance |
| Credit | █████ | Overall repayment history |
| Debts | █████ | Required monthly obligations |
| Residual income | █████ | Money remaining after obligations |
| Assets | █████ | Closing funds and reserves |
No single category tells the whole story. A veteran with higher monthly debt may have strengths elsewhere, while excellent credit doesn’t solve an income or entitlement issue.
How Does The Certificate Of Eligibility Affect Preapproval?
The Certificate of Eligibility confirms that you meet the service-related eligibility requirements for the VA home loan benefit, but it doesn’t mean the mortgage itself is approved.
The VA currently describes obtaining the COE as “the first step” in getting a VA-backed home loan. Its July 24, 2026 guidance explains that veterans may need a DD214, while active-duty service members generally need a statement of service. National Guard, Reserve, and eligible surviving-spouse documentation varies by situation. Veterans Affairs
A COE can also contain entitlement information that matters when you’ve used the VA benefit before.
I’d rather identify a COE or entitlement question before you’re negotiating on a house. It’s much easier to sort out when there isn’t a closing deadline hanging over the process.
What Financial Information Gets Reviewed?
A VA preapproval generally reviews usable income, recurring debts, credit history, available assets, projected housing expenses, and residual income.
That can include:
- Employment and income documentation
- Bank and asset statements
- Student and auto loans
- Credit card payments
- Property taxes and insurance
- HOA or condo dues
- Funds needed for closing
- Other recurring obligations
For someone with variable pay, multiple jobs, a recent employment transition, or business income, determining which income is stable and usable can require a closer review.
Can Self-Employed Veterans Get VA Mortgage Pre Approval?
Yes, self-employed veterans can receive VA Mortgage Pre Approval when their income and overall financial profile meet the applicable requirements.
Self-employment often requires a deeper review because business revenue isn’t the same as qualifying personal income. Depending on the situation, documentation may include personal and business tax returns, ownership information, profit-and-loss statements, and evidence showing whether income is stable and likely to continue.
Our explanation of how self-employed income is evaluated for a mortgage covers why money deposited into a business account isn’t automatically the amount used for qualification. The Doce Mortgage Group
I’ve learned not to judge a self-employed veteran’s situation from gross revenue or 1 line on a tax return. The useful question is what the complete documentation supports after the business income is properly analyzed.
How Are Military And Nontraditional Income Sources Evaluated?
VA preapproval can consider several types of military and nontraditional income, but each income source must be properly documented and considered stable enough to use.
Depending on your situation, usable income may include:
- Active-duty base pay
- Basic Allowance for Housing
- Basic Allowance for Subsistence
- VA disability compensation
- Military retirement income
- Civilian employment income
- Overtime or bonuses
- Commission income
- Part-time employment
- Self-employment income
The rules aren’t identical for every income source. For example, VA’s official income guidance generally looks for a history of overtime, part-time, and bonus income, while VA disability compensation can be treated differently because of its nature and expected continuance.
| Income Type | Documentation That May Be Reviewed |
|---|---|
| Active-duty pay | LES and service documentation |
| VA disability | VA benefit documentation |
| Military retirement | Award and payment records |
| W-2 employment | Pay stubs and W-2s |
| Self-employment | Tax and business records |
| Commission or bonus | Earnings history and current income |
VA reported in May 2026 that veterans have received more than 29 million VA home loans since the program began. That enormous range of borrowers is another reason veterans shouldn’t assume they need a perfectly traditional financial profile to explore their benefit.
How Does VA Residual Income Help Veterans With Higher DTI?
Residual income can strengthen the overall analysis by showing how much money remains each month after major obligations and housing expenses are considered.
Debt-to-income ratio, or DTI, compares recurring monthly debt with gross monthly income. It’s important, but VA underwriting also places special emphasis on residual income.
Residual income considers expenses such as:
- Proposed housing costs
- Installment and revolving debt
- Taxes
- Certain recurring obligations
- Household size
- Geographic region
The idea is practical. Two veterans can have the same DTI but very different amounts of money remaining for food, transportation, utilities, and everyday expenses.
Our explanation of how debt-to-income ratio is calculated can help you understand how those recurring obligations affect qualification.
I often tell veterans not to disqualify themselves because of 1 ratio. A higher DTI deserves careful review, but the complete VA financial analysis matters more than looking at a single percentage by itself.
Can You Get VA Preapproval With Credit Problems?
Yes, veterans with past credit problems may still qualify for VA Mortgage Pre Approval, depending on the severity, timing, cause, and more recent credit history.
The Department of Veterans Affairs itself doesn’t establish a universal minimum credit score for VA-backed purchase financing. Credit history is still evaluated, and individual mortgage programs can establish additional requirements.
A review may consider:
- Recent late payments
- Collections
- Charge-offs
- Limited credit history
- Bankruptcy
- Foreclosure
- Re-established credit
- Circumstances behind a major credit event
At The Doce Mortgage Group, our Florida VA loan program currently offers qualifying options with FICO scores as low as 580.
A score alone doesn’t guarantee approval. Recent payment behavior, debts, income stability, residual income, and the complete credit history still matter.
What If You’re Transitioning From Military To Civilian Employment?
A transition from military service to civilian employment can still work for VA financing, but the timing and documentation of the new income need careful review.
Important details can include:
- Military separation date
- Civilian employment start date
- New salary
- Written employment offer
- Employment history
- Gaps between positions
- Military retirement income
- Continuing Reserve or Guard income
VA guidance doesn’t automatically reject someone simply because they’ve been in a current position for less than 1 year. Employment history, stability, and the circumstances surrounding the transition can be evaluated.
I’ve worked with veterans whose employment change looked concerning until we laid out the timeline clearly. In situations like this, dates and documentation often matter as much as the job change itself.
How Do Student Loans And Other Debts Affect VA Preapproval?
Recurring debts can affect both DTI and residual income, so the monthly obligation associated with each debt needs to be identified accurately.
Common obligations include:
- Student loans
- Auto payments
- Credit cards
- Personal loans
- Child support
- Alimony
- Co-signed debt
- Other installment payments
Don’t assume a deferred student loan or a debt someone else pays can simply be ignored. The documentation and circumstances determine how an obligation is treated.
This is also why veterans with complicated finances benefit from completing the financial review early. You can begin through our secure application portal so we can evaluate the actual debts and income rather than relying on rough estimates.
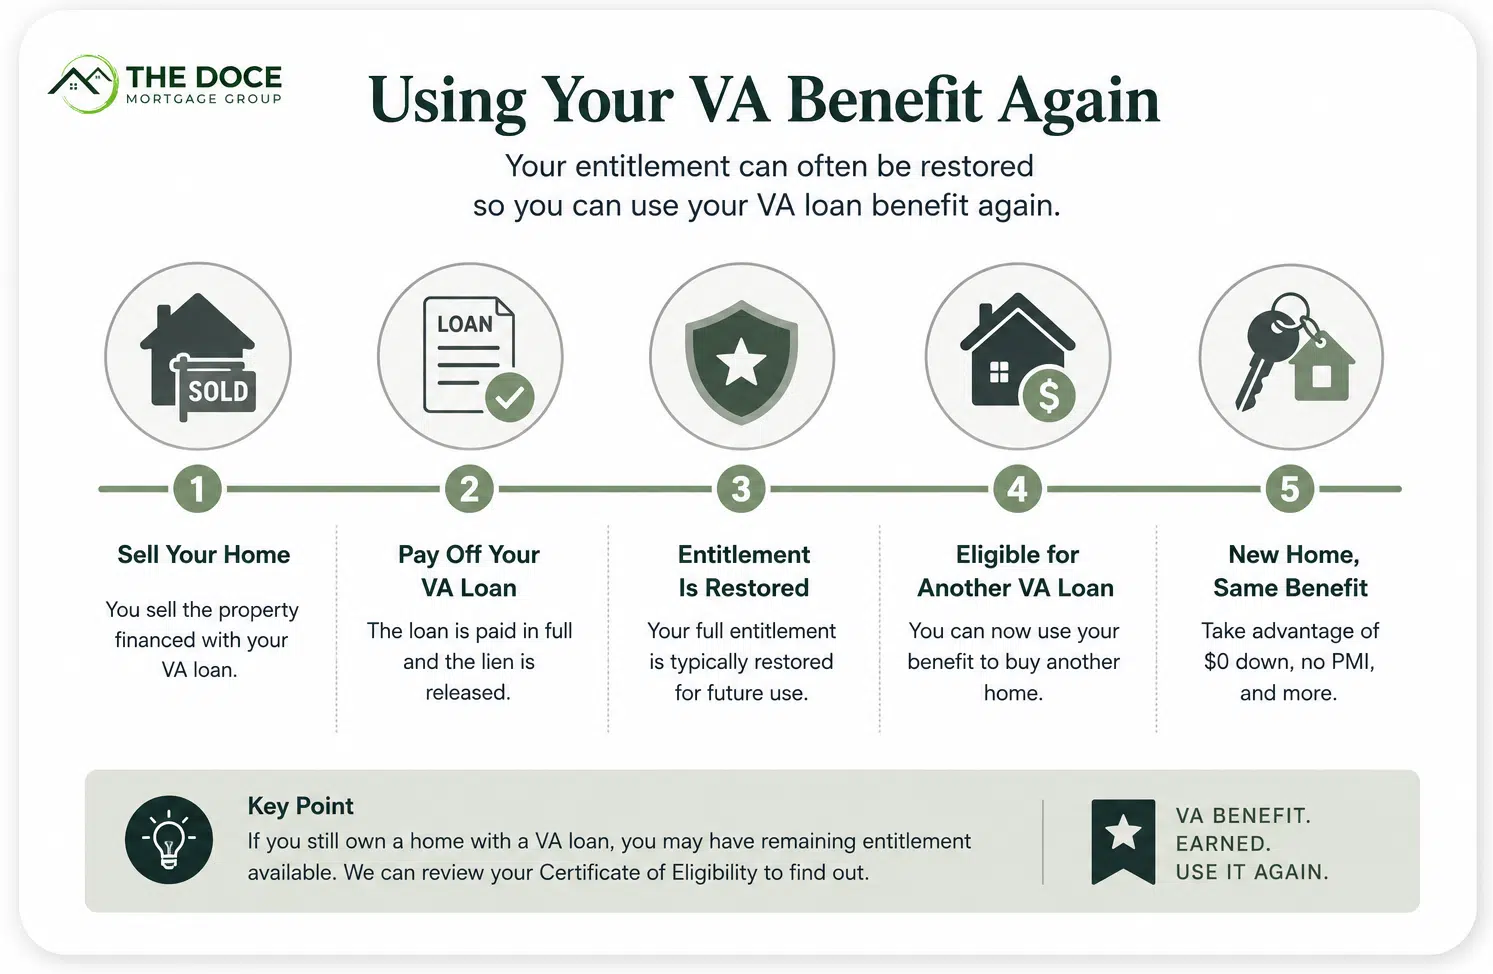
What If You’ve Already Used Your VA Benefit?
Using your VA home loan benefit before doesn’t automatically prevent you from using it again.
A veteran may have full entitlement available, remaining entitlement, or may be able to restore previously used entitlement after certain conditions are satisfied.
Situations that deserve early review include:
| Situation | What Needs To Be Reviewed |
|---|---|
| Previous VA home sold | Whether entitlement was restored |
| Existing VA mortgage | Remaining available entitlement |
| Previous mortgage paid off | Restoration eligibility |
| Keeping previous property | Available entitlement for next purchase |
| Prior VA loss | Current entitlement status |
This is one of the areas where assumptions can become expensive. I’ve seen veterans believe they couldn’t use VA financing again simply because they still owned a previous home. The better approach is to review the COE and actual entitlement before deciding what purchase options are available.
How Much Can You Be Preapproved For With A VA Loan?
Your VA preapproval amount depends on what your income, debts, residual income, credit profile, projected housing expenses, and available entitlement support.
There isn’t 1 universal maximum purchase price for every veteran. Your affordable range can change based on:
- Interest rate
- Monthly qualifying income
- Existing debt payments
- Property taxes
- Homeowners insurance
- HOA or condo dues
- Residual income
- Available VA entitlement
- VA funding fee
- Any required down payment
VA financing can allow eligible veterans to purchase with no down payment, which can make the program especially useful for someone who has strong income but wants to preserve savings. Our guide to buying a Florida home with no money down explains how VA financing fits among the available 0% down options.
I tell veterans not to treat the highest preapproval amount as a spending target. What you qualify for and what feels comfortable every month can be 2 different numbers.
VA Funding Fee And Cash-To-Close Considerations
A VA purchase can require money at closing even when no down payment is required.
Many VA borrowers pay a one-time funding fee. According to the VA’s current 2026 funding fee guidance, the percentage depends partly on your down payment and whether you’ve used the VA benefit before.
VA Purchase Funding Fee Comparison Chart
| Down Payment | First Use | After First Use |
|---|---|---|
| Under 5% | ██████ 2.15% | █████████ 3.30% |
| 5% or more | ████ 1.50% | ████ 1.50% |
| 10% or more | ███ 1.25% | ███ 1.25% |
The funding fee can generally be financed into the mortgage or paid at closing.
Some borrowers are exempt. In June 2026, VA reported that more than half of veterans who had received VA-guaranteed home loans since 2021 were exempt from the funding fee. Common exemptions include qualifying veterans receiving compensation for a service-connected disability.
Even with $0 down, you may still need funds for items such as:
- Prepaid property taxes
- Homeowners insurance
- Escrow deposits
- Appraisal-related expenses
- Title and settlement charges
- Other permitted closing costs
That distinction is important when preparing a VA Mortgage Pre Approval because $0 down doesn’t automatically mean $0 cash to close.
Pros And Cons Of VA Preapproval For Complex Financial Profiles
| Pros | Cons |
|---|---|
| Problems can be identified early | Complex income may require more records |
| Residual income adds important context | Preapproval isn’t final approval |
| Clarifies a realistic purchase range | Financial changes can affect results |
| Reviews entitlement before an offer | Property approval still matters |
| VA may allow $0 down | Some borrowers pay a funding fee |
For veterans with unusual finances, getting the details reviewed early can be especially valuable because it provides time to resolve documentation questions before a purchase contract creates deadlines.
Myths Vs Facts
Myth: A high DTI automatically disqualifies every veteran
Fact: Residual income and the overall financial profile also matter
Myth: Self-employed veterans can’t use VA financing
Fact: Properly documented self-employment income can qualify
Myth: A COE means the mortgage is approved
Fact: It confirms benefit eligibility, not final financial approval
Myth: You can use your VA benefit only once
Fact: Entitlement can often be restored or reused
Myth: VA financing requires perfect credit
Fact: Credit is evaluated as part of the complete financial picture
Common Mistakes
- Waiting until under contract to check entitlement
- Assuming unusual income can’t qualify
- Changing jobs without reviewing the timing
- Opening new credit after preapproval
- Moving large sums without documentation
- Ignoring residual income
- Underestimating taxes and insurance
- Assuming $0 down means $0 closing cash
- Forgetting about co-signed obligations
- Treating preapproval as guaranteed final approval
One of the biggest mistakes I see is changing something after preapproval without considering the effect. A new car payment, credit card balance, job change, or unexplained transfer can alter the financial picture that supported the original decision.
Key Facts
- A COE confirms VA benefit eligibility
- Financial qualification is reviewed separately
- VA financing doesn’t require monthly PMI
- Self-employed veterans may qualify
- Residual income is an important VA measure
- Higher DTI doesn’t automatically mean denial
- VA entitlement can often be reused
- Funding fee exemptions are available
- Preapproval can change before closing
How Can The Doce Mortgage Group Help With A Complex VA Preapproval?
We’ve spent more than 38 years helping buyers work through mortgage situations that don’t always fit neatly into a standard box. With VA financing, we can review your entitlement, income, employment history, debts, residual income, credit circumstances, and expected housing payment before you begin making offers.
For veterans with self-employment income, military-to-civilian employment transitions, higher debt, prior credit events, or existing VA financing, our goal is to identify the important questions early and explain your options clearly. You can see what clients have said about working with us through our customer reviews.
The Doce Mortgage Group was also recently recognized as one of the best mortgage brokers in several cities throughout Florida. You can get a free quote from our team based on your actual circumstances.
When you’re ready to move forward, you can Get Started Now, or connect with a loan officer live at 305-661-3434.