Quick Answer
Renting can be better when flexibility and lower upfront costs matter most. Buying may be better when you expect to stay longer, can comfortably afford ownership, and want to build equity.
Comparing Rent Vs Mortgage isn’t as simple as comparing your rent with a quoted mortgage payment. A fair comparison needs to include down payment, closing costs, taxes, insurance, maintenance, future rent increases, home equity, and how long you expect to stay. Your lifestyle plans matter just as much as the numbers.
A Personal Story
I worked with a renter who assumed buying would cost far more because he compared his $2,000 monthly rent with a projected mortgage payment. Once we looked at what each payment included, how rent might change, the equity he could build, and how long he expected to stay, the decision looked completely different.
My advice is to stop asking only, “Which payment is lower today?” I prefer to ask where you’ll likely be financially after 5, 7, or 10 years. That usually leads to a much more useful answer.
What Does Rent Vs Mortgage Really Compare?
Rent Vs Mortgage compares the complete financial and lifestyle effects of renting a home with owning one through mortgage financing.
Rent primarily pays for the right to occupy a property during your lease. With homeownership, part of your mortgage payment may reduce the principal balance and increase your ownership in the property.
A typical monthly housing cost can include much more than principal and interest.
What Your Monthly Housing Payment Does
| Housing Cost | Renting | Buying |
|---|---|---|
| Monthly Payment | Pays for occupancy | Pays housing and financing costs |
| Principal | None | Can build ownership |
| Interest | None directly | Cost of financing |
| Property Taxes | Usually built into rent indirectly | Homeowner responsibility |
| Insurance | Renters insurance | Homeowners insurance |
| Maintenance | Often property owner’s responsibility | Homeowner responsibility |
| Equity | None from rent payments | Can grow over time |
One important detail is that a fixed-rate mortgage doesn’t make every housing expense permanently fixed. Principal and interest can remain stable, while property taxes, homeowners insurance, HOA dues, and other ownership expenses may change.
How Much Does Renting Really Cost Over Time?
Renting costs more than the advertised monthly rent once you consider rent increases, fees, moving costs, and the absence of home equity.
Zillow reported that the typical U.S. asking rent reached $1,962 in July 2026, up 2.3% from a year earlier. Florida markets varied considerably, including approximately $2,013 in Tampa, $1,959 in Orlando, and $1,711 in Jacksonville.
Renters may also face:
- Security deposits
- Application fees
- Pet fees
- Parking charges
- Utility costs
- Moving expenses
- Lease renewal increases
Renting still has real advantages. Zillow also reported that 39.8% of rental listings nationally offered some type of concession in July 2026, which shows that renters may have negotiating power in some markets.
I don’t consider rent “wasted money.” You’re paying for housing, flexibility, and freedom from many repair responsibilities. The question is whether those benefits outweigh what you might gain from ownership.
What Costs Come With Owning a Home?
Homeownership includes the mortgage payment plus taxes, insurance, maintenance, and sometimes HOA expenses.
Renting Vs Owning Costs
| Expense | Renter | Homeowner |
|---|---|---|
| Upfront Cash | Usually lower | Usually higher |
| Property Taxes | Indirectly reflected in rent | Direct responsibility |
| Insurance | Usually lower-cost renters coverage | Homeowners coverage |
| Maintenance | Usually limited | Homeowner responsibility |
| Major Repairs | Usually property owner’s responsibility | Homeowner responsibility |
| HOA | Usually incorporated into rent | May be separate |
| Equity Potential | None | Yes |
| Selling Costs | None | Possible when selling |
Florida homeowners also need to pay particular attention to property insurance. Premiums can vary significantly depending on location, roof age, construction, wind mitigation, flood exposure, and the property itself.
I’ve always believed that qualifying for a payment and comfortably affording it are 2 different things. I don’t want someone becoming house-rich and cash-poor simply because the numbers technically work.
Understanding how much home you can comfortably afford means looking beyond the mortgage payment and leaving room for real life.
How Does Your Time Horizon Change the Answer?
How long you expect to stay is one of the most important factors in deciding whether renting or buying makes more financial sense.
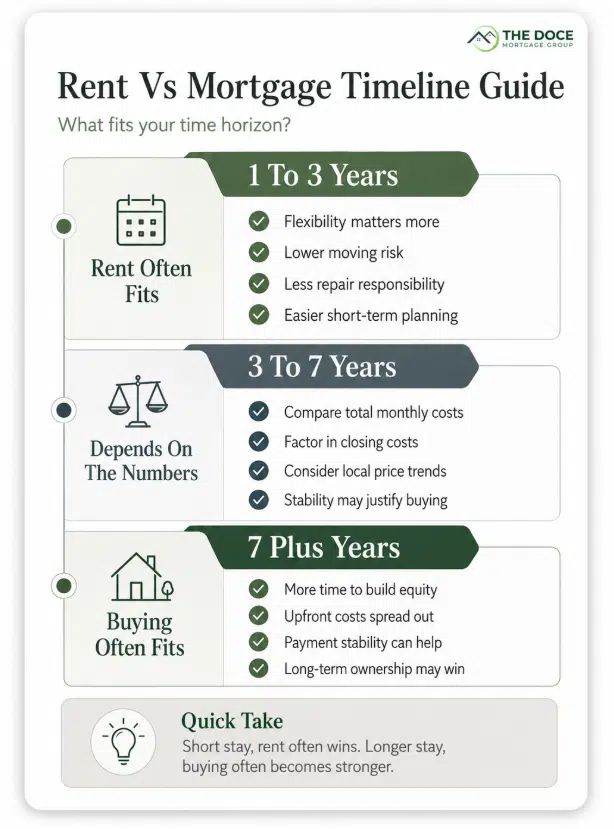
Buying has upfront transaction costs and may eventually involve selling expenses. That means buying a home you expect to leave in 18 months can produce a very different result from buying one you expect to keep for 10 years.
There isn’t a universal rule that buying becomes better after exactly 5 years. Your break-even point depends on rent, home price, down payment, mortgage rate, taxes, insurance, maintenance, appreciation, rent increases, and selling costs.
You can compare those variables using our Rent vs. Buy Calculator to estimate when buying may overtake renting based on your own numbers.
How Does a Mortgage Build Equity?
A mortgage can build equity because part of each payment reduces the principal balance you owe, while the home’s value may also increase over time.
Suppose you buy a $400,000 home with a $380,000 mortgage. As you make payments, the principal balance gradually falls. If the home’s market value also rises, your equity can grow from both directions.
Equity isn’t guaranteed profit. Home values can fall, and selling a home involves costs. You also can’t spend equity like money in a checking account unless you sell, refinance, or qualify to borrow against it.
I like to remind buyers that principal reduction is one of the biggest differences in a Rent Vs Mortgage comparison. Rent gives you housing for the month. A portion of a mortgage payment can increase the share of the home you own.
How Do Current Mortgage Rates Affect Rent Vs Mortgage?
Mortgage rates can change the monthly cost of buying significantly, which can move the break-even point between renting and owning.
As of August 27, 2026, Freddie Mac reported an average 30-year fixed mortgage rate of 6.66% and a 15-year average of 5.98%. These are national averages, not rates that every buyer will receive. Freddie Mac
A $350,000 mortgage at 6.0% has a very different principal-and-interest payment from the same mortgage at 7.0%. That difference affects affordability today and how quickly buying may become financially competitive with renting.
Rates also shouldn’t be viewed in isolation. A buyer may find a home at a better price when rates are higher, or may later have an opportunity to refinance if market conditions improve. Neither outcome should be assumed in advance.
How The Same Home Can Produce Different Decisions
| Situation | Renting May Look Better When | Buying May Look Better When |
|---|---|---|
| Expected Stay | Short | Long |
| Current Rent | Low | High |
| Purchase Costs | High | Manageable |
| Mortgage Rate | Higher | Lower |
| Cash Reserves | Limited | Comfortable |
| Maintenance | Want fewer responsibilities | Prepared for ownership |
| Location Plans | Likely to change | Stable |
The point isn’t that 1 column automatically wins. A few changed assumptions can completely alter the result.
How Much Does a Down Payment Change the Comparison?
Your down payment changes the amount financed, monthly payment, mortgage insurance, cash needed at closing, and how much money you keep available after buying.
Putting 20% down can reduce the mortgage balance and may eliminate conventional private mortgage insurance, but 20% isn’t required for many buyers. Our conventional mortgage options may allow qualifying buyers to purchase with substantially less, while FHA financing may allow as little as 3.5% down.
The larger question is what happens to the cash you don’t put into the home. Keeping $30,000 in reserves may be more valuable to 1 buyer than reducing the monthly payment further. Another buyer may prefer the smaller mortgage and lower monthly expense.
One of the most persistent Florida down payment myths is that everyone needs 20% down. The right down payment is the amount that creates a comfortable payment while still leaving you financially prepared after closing.
Can You Buy a Home Without a Large Down Payment?
Yes, qualifying buyers may have mortgage options requiring a small down payment or even 0% down.
That can materially change a Rent Vs Mortgage comparison for someone who assumed they needed years to save 20%.
Low Down Payment Options To Consider
| Option | Potential Down Payment | Who It May Fit |
|---|---|---|
| Conventional | As low as 3% | Qualifying buyers seeking standard financing |
| FHA | As low as 3.5% | Buyers wanting flexible qualification |
| VA | Potentially 0% | Eligible veterans and service members |
| USDA | Potentially 0% | Eligible buyers and properties |
| HomeZero | Potentially 0% | Qualifying Florida buyers |
| Florida DPA | Varies | Buyers needing help with upfront costs |
The Doce Mortgage Group’s HomeZero Program can provide a 100% financing structure for qualifying Florida buyers. We also work with Florida down payment assistance programs when they fit the buyer and mortgage.
Low down payment doesn’t automatically mean low cost. Mortgage insurance, interest rate, closing costs, reserves, and the complete monthly payment still need to be compared.
If buying appears competitive with your rent, you can start through our secure application portal so we can compare the financing options available to you instead of relying on broad estimates.
When is Renting the Better Choice?
Renting can be the better choice when flexibility, lower upfront costs, or preserving cash matters more than building home equity.
Renting may fit you better if:
- You expect to move within a few years
- Your job location may change
- Your emergency savings are limited
- Local purchase prices are unusually high
- You don’t want maintenance responsibility
- You value flexibility more than ownership
There’s nothing financially irresponsible about renting when it fits your circumstances. Buying too early, then selling 2 years later, can sometimes cost more than simply renting during that period.
When is Buying the Better Choice?
Buying can make more sense when you expect to stay long enough, can comfortably handle ownership expenses, and want the opportunity to build equity.
Florida Realtors reported a statewide single-family median sale price of $425,000 in July 2026, up 3.7% from a year earlier. That doesn’t mean every Florida market is appreciating at the same pace, but it shows why home price and expected ownership period belong in the comparison.
Buying may fit better when:
- Your location is relatively stable
- You expect to stay several years
- You have adequate emergency reserves
- The full payment fits comfortably
- You want control over the property
- Building equity is important to you
I’ve worked with buyers who were surprised to discover that ownership became attractive even though the monthly payment started somewhat higher than rent. The longer time horizon changed the calculation.
Rent Vs Mortgage Decision Snapshot
| Priority | Renting May Fit Better | Buying May Fit Better |
|---|---|---|
| Flexibility | High priority | Lower priority |
| Expected Stay | Short | Long |
| Upfront Cash | Want to preserve it | Adequate funds available |
| Maintenance | Want fewer responsibilities | Comfortable handling it |
| Equity Building | Lower priority | Important |
| Property Control | Less important | Important |
| Location Plans | Likely to change | Relatively stable |
Pros and Cons of Renting Vs Buying
Renting offers lower upfront costs, easier relocation, and fewer repair responsibilities. The tradeoff is that rent doesn’t build home equity, future increases are possible, and you have less control over the property.
Buying can provide equity growth, more control over the home, and stable principal and interest with a fixed-rate mortgage. The tradeoffs include closing costs, maintenance, property taxes, insurance, and the expense of selling if you move.
Some buyers also use strategies such as a 2-1 buydown to reduce payments during the first 2 years of ownership when that structure fits the transaction.
Myths Vs Facts
Myth: Renting is always wasting money
Fact: Rent pays for housing, flexibility, and fewer ownership responsibilities
Myth: Buying is always cheaper
Fact: Short ownership periods can make buying more expensive
Myth: You need 20% down
Fact: Many mortgage programs require considerably less
Myth: A fixed mortgage means your total payment never changes
Fact: Taxes, insurance, and HOA expenses can still change
Myth: Home prices always increase
Fact: Property values can rise or fall
Common Mistakes
- Comparing rent only with principal and interest
- Ignoring homeowners insurance
- Forgetting maintenance and repairs
- Assuming future appreciation
- Ignoring potential rent increases
- Draining savings for a down payment
- Forgetting future selling costs
- Buying when you expect to move soon
Key Facts
- Rent and mortgage payments aren’t directly comparable
- Homeownership can build equity
- Renting usually provides greater mobility
- Buying usually requires more upfront cash
- Taxes and insurance can increase
- Your time horizon strongly affects the answer
- Low-down-payment options can change the comparison
- Neither choice is automatically better
How Can The Doce Mortgage Group Help
We’ve spent more than 38 years helping Florida buyers compare the real cost of renting with the complete cost of homeownership. We can evaluate your rent, expected time in the home, down payment, mortgage insurance, taxes, insurance, and available conventional, FHA, VA, USDA, HomeZero, and down payment assistance options.
You can see what clients have said about working with us through our customer reviews. The Doce Mortgage Group was also recently recognized with the prestigious WalletHub Award as one of the best mortgage brokers in several cities throughout Florida.
If you want us to compare your numbers directly, you can get a free quote and we’ll help you evaluate the options.
When you’re ready to move forward, you can Get Started Now, or connect with a loan officer live at 305-661-3434.