Quick Answer
A hard money loan in Florida can make sense when speed, property condition, or short-term flexibility matters more than getting the lowest financing cost. It’s most useful when there’s a clear reason for short-term financing and a realistic plan to repay or refinance it.
Hard money isn’t automatically a good or bad choice. It’s a specialized financing tool that can be valuable when a property or transaction doesn’t fit a slower, more traditional path. However, the added cost and shorter timeline mean the numbers need to make sense from the beginning.
Alex’s Professional Insights
I’ve worked with Florida investors who found properties with strong potential but serious condition problems and sellers who wanted to close quickly. In those situations, the obstacle wasn’t always credit or income. The bigger problem was finding financing that could work with the property as it stood and meet the seller’s deadline.
My advice is to start with the exit strategy, not the excitement of getting the deal. I want to know how the renovation gets finished, what the property should conservatively be worth afterward, and exactly how the short-term financing will be paid off.
What Is A Hard Money Loan In Florida?
A hard money loan is generally short-term real estate financing that places heavy emphasis on the property, available equity, transaction structure, and repayment plan.
Instead of looking only at the borrower’s traditional income profile, hard money financing may focus more heavily on the real estate securing the transaction. That can make it useful for investment properties that need major repairs, unusual transactions, or purchases that need to close quickly.
Terms vary widely, but hard money financing may include:
- Shorter repayment periods
- Higher interest rates than traditional mortgages
- Upfront origination points
- Interest-only payments in some structures
- Renovation funds in some programs
- Greater focus on property value
- A clearly defined exit strategy
The important point is that hard money isn’t simply a faster version of a conventional mortgage. The qualification process, costs, repayment timeline, and intended use can be very different. It’s a good idea to understand the differences between hard money and traditional mortgage financing.
Florida’s housing market also creates a wide range of possible investment situations. According to Florida Realtors, 75,080 existing single-family homes sold statewide in Q2 2026, up 4.1% from the same quarter in 2025. The statewide median single-family sale price was $425,000.
When Does A Hard Money Loan In Florida Make Sense?
A hard money loan usually makes the most sense when speed or property flexibility creates enough value to justify the higher financing cost.
Common situations include:
- Fix-and-flip purchases
- Distressed properties
- Major renovation projects
- Auction purchases
- Very short closing deadlines
- Short-term bridge needs
- Properties needing repairs before refinancing
- Rentals that need stabilization first
- Credit issues
- Unable to document income or assets
- Recent bankruptcy
For example, an investor might find a property that needs substantial electrical, roofing, plumbing, or structural work before it fits a long-term mortgage program. Hard money may provide a way to purchase and repair the property first, then refinance once the work is complete.
Speed can matter too. A seller may prefer an offer that can close quickly, especially when the property is vacant, distressed, inherited, or being sold as-is. In that situation, the financing cost has to be weighed against the value of securing the property.
I look at hard money as a problem-solving tool. If there’s no specific problem that requires the added flexibility, a lower-cost long-term option may be the better choice.
Chart 1: Typical Hard Money Fit By Scenario
| Scenario | Typical Fit |
|---|---|
| Heavy renovation property | Very strong |
| Fix-and-flip | Very strong |
| Extremely fast closing | Very strong |
| Short bridge need | Strong |
| Stabilized rental | Moderate |
| Long-term primary home | Weak |
This chart provides general guidance only. The right structure depends on the property, transaction, borrower, and intended use.
What Do Hard Money Providers Evaluate?
Property value is important, but a strong property alone usually isn’t enough to make a hard money transaction work.
Depending on the program and transaction, the review may include:
- Current property value
- Expected after-repair value
- Down payment or available equity
- Renovation scope and budget
- Cash reserves
- Real estate experience
- Credit profile
- Property insurance
- Title condition
- Project timeline
- Exit strategy
The exit strategy is especially important. A plan to sell after renovation is different from a plan to refinance into a DSCR, conventional, or Non-QM mortgage. Each path has its own timing and qualification risks.
A property can look profitable on paper and still become a bad hard money deal if the renovation runs over budget, permits are delayed, insurance costs rise, or the planned refinance doesn’t work.
You can start through our secure application portal so we can review the property, your timeline, and the financing options that may fit the transaction.
What Costs And Terms Should You Compare?
You should compare the total financing cost, repayment timeline, and extension terms, not just the advertised interest rate.
Hard money is usually short-term financing, so seemingly small differences in fees or holding time can have a major effect on the final cost. Before choosing an option, review every charge and ask how the cost changes if the project takes longer than planned.
Important items to compare include:
- Interest rate
- Origination points
- Processing fees
- Property valuation costs
- Title and closing expenses
- Interest-only payment requirements
- Minimum interest provisions
- Extension fees
- Prepayment terms
- Renovation draw fees
- Inspection charges
- Default interest
- Required reserves
Points deserve special attention. One point equals 1% of the amount financed. On a $300,000 balance, 2 points equal $6,000 before you’ve paid any monthly interest.
The holding period matters just as much. ATTOM reported that the typical home flipped during Q1 2026 took 165 days from purchase to resale. That was slightly longer than both the previous quarter and Q1 2025. A project expected to take 90 days can therefore become much more expensive if renovations, permits, inspections, or the resale take several additional months.
Chart 2: Why Holding Time Matters
The following example assumes a $300,000 balance at an illustrative 12% interest-only rate with 2 points. It isn’t a current rate quote.
| Holding Period | Interest Cost | 2 Points | Combined Cost |
|---|---|---|---|
| 3 months | $9,000 | $6,000 | $15,000 |
| 6 months | $18,000 | $6,000 | $24,000 |
| 9 months | $27,000 | $6,000 | $33,000 |
| 12 months | $36,000 | $6,000 | $42,000 |
These figures don’t include property taxes, insurance, renovation costs, closing expenses, extension charges, utilities, HOA costs, or selling expenses.
I’ve seen investors spend a lot of time negotiating the purchase price while barely looking at carrying costs. I recommend stress-testing the project for several extra months before deciding that the numbers work.
Hard Money Vs Other Florida Financing Options
Hard money may be strongest when speed or property condition is the problem, while other mortgage options can make more sense for longer-term ownership.
| Financing Option | Often Best Suited For | Main Qualification Focus | Typical Strategy |
|---|---|---|---|
| Hard money | Fast or difficult transactions | Property and exit strategy | Short term |
| DSCR | Income-producing rentals | Property rental income | Buy and hold |
| Conventional | Qualified long-term borrowers | Full financial profile | Long term |
| Non-QM | Complex income situations | Alternative documentation | Medium or long term |
For example, an investor purchasing a stabilized rental may not need expensive short-term financing simply because the property is an investment. A Florida DSCR loan can instead focus heavily on the property’s rental income when determining whether the investment supports its mortgage obligations. The Doce Mortgage Group’s current DSCR program is specifically designed for rental-property investors.
Non-QM financing can also help borrowers with unusual income documentation, including self-employed borrowers and some real estate investors. The Doce Mortgage Group offers Florida Non-QM mortgage options for situations where traditional documentation doesn’t tell the whole financial story.
Hard money becomes more compelling when the property itself creates the obstacle. A house with major damage may need to be repaired before it fits a long-term program. In that case, short-term financing can potentially serve as the bridge between acquisition and permanent financing.
When evaluating a rental property, you can also use our DSCR Loan Calculator to estimate how the property’s rental income compares with its housing obligations.
The right structure also depends on the investment itself. Florida investors need to account for insurance, property taxes, vacancy, maintenance, HOA costs, and realistic rental income when purchasing an investment property in Florida.
Why Is The Exit Strategy So Important?
A hard money loan works best when there’s a realistic and well-planned way to repay it before the short term becomes expensive or expires.
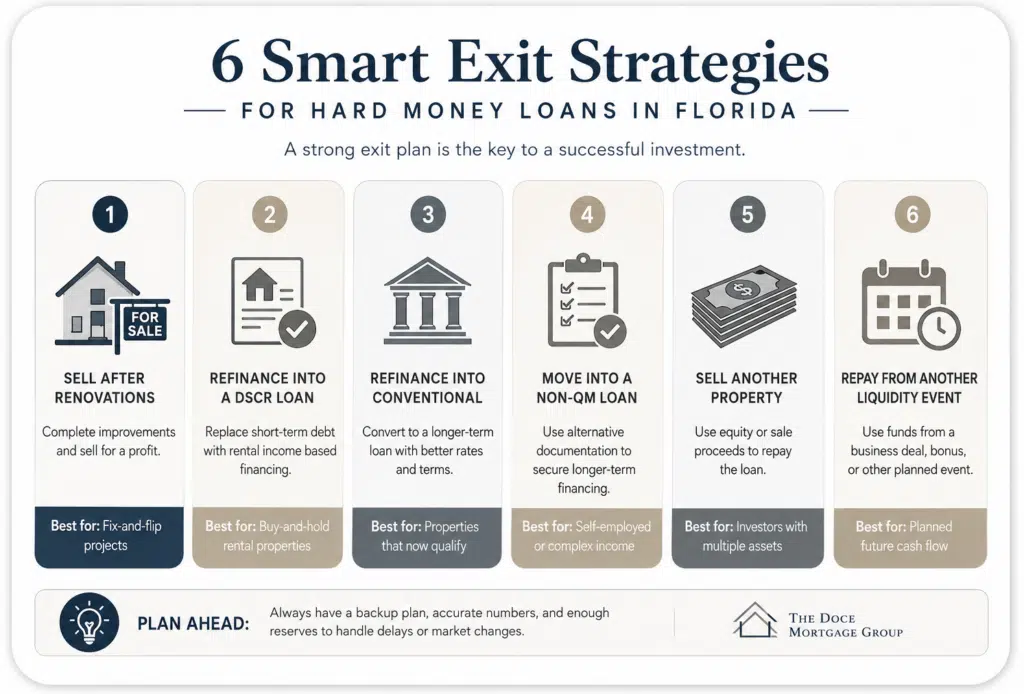
Common exit strategies include:
- Sell after completing renovations
- Refinance into a DSCR mortgage
- Refinance into conventional financing
- Move into an appropriate Non-QM program
- Sell another property
- Repay from another planned liquidity event
Before closing, I’d want to know not only the preferred exit strategy, but also the backup plan.
| Exit Strategy Question | What You Should Verify |
|---|---|
| When will renovations finish? | Contractor and permit timeline |
| What if work runs late? | Reserves and extension costs |
| What will the property be worth? | Conservative comparable sales |
| Can it qualify for refinancing? | Program requirements beforehand |
| Will the rent support financing? | Realistic market rent |
| What if resale takes longer? | Carrying-cost reserves |
| What Florida costs could rise? | Insurance, HOA, taxes, repairs |
Federal consumer-credit rules also distinguish some investment-property transactions from consumer-purpose financing. Consumer Financial Protection Bureau guidance says credit used to acquire, improve, or maintain a non-owner-occupied rental property is generally treated as business-purpose credit under Regulation Z. That makes it especially important to understand the exact purpose, terms, protections, and obligations of the financing before signing.
A strong exit strategy shouldn’t depend on everything going perfectly. If the project only works with a flawless renovation, immediate resale, perfect appraisal, and instant refinance, the margin for error may be too small.
Pros And Cons
Hard money can be a powerful financing tool when speed, flexibility, or property condition creates a problem that other options can’t solve quickly.
Pros:
- Faster closing timelines
- More flexibility with property condition
- Greater focus on the real estate
- Useful for major renovations
- Can work for unusual properties
- Helpful in competitive investment situations
- May bridge the gap to long-term financing
Cons:
- Higher interest costs
- Upfront points can be significant
- Short repayment periods
- Extension fees may apply
- Delays can become expensive
- Carrying costs can reduce profits
- A strong exit strategy is essential
I generally think hard money works best when you can clearly explain why you need it. If the answer is simply that it’s available, that isn’t enough. There should be a specific benefit, such as securing a distressed property, completing renovations, meeting a tight closing deadline, or creating a path toward better long-term financing.
Myths Vs Facts
Myth: Hard money is only for borrowers with poor credit
Fact: Investors with strong credit may use hard money because they need speed, renovation flexibility, or financing for a difficult property.
Myth: Property value is the only thing that matters
Fact: Equity, liquidity, renovation plans, experience, reserves, credit, and the exit strategy can also affect the decision.
Myth: Hard money is always the best choice for investment properties
Fact: A stabilized rental may be better suited to a Florida DSCR loan, conventional financing, or another long-term option.
Myth: A profitable flip automatically justifies expensive financing
Fact: Interest, points, renovations, taxes, insurance, utilities, selling expenses, and delays can consume a large part of the projected profit.
Myth: Refinancing out of hard money is guaranteed
Fact: The property and borrower still need to qualify for the planned replacement financing when the time comes.
Understanding Florida DSCR loan qualifications before entering the short-term transaction can make a future rental refinance more predictable.
Common Mistakes
The biggest hard money mistakes usually happen when buyers underestimate time, costs, or risk.
Common problems include:
- Looking only at the interest rate
- Ignoring upfront points
- Underestimating renovation costs
- Using an unrealistic after-repair value
- Forgetting permit delays
- Overestimating resale speed
- Ignoring extension fees
- Underestimating Florida insurance costs
- Forgetting flood insurance exposure
- Missing HOA or condo assessments
- Underestimating taxes and utilities
- Having only 1 exit strategy
- Assuming future refinancing will be easy
One mistake I see investors make is building the entire deal around the best possible outcome. I’d rather see the numbers work with a conservative resale value, extra renovation costs, and several additional months of carrying expenses.
Florida Investor Activity In 2026
Florida continues to attract significant real estate investor activity, but the level varies dramatically by market.
According to Redfin’s Q1 2026 investor analysis, investors represented 33% of home purchases in Miami among the metros it tracked. Other major Florida markets also showed meaningful investor activity.
Chart 3: Investor Share Of Q1 2026 Home Purchases
Miami             ¦¦¦¦¦¦¦¦¦¦¦¦¦¦¦¦¦  33%
Orlando           ¦¦¦¦¦¦¦¦¦¦¦        21%
Fort Lauderdale   ¦¦¦¦¦¦¦¦¦¦         20%
West Palm Beach   ¦¦¦¦¦¦¦¦¦¦         20%
Tampa             ¦¦¦¦¦¦¦¦¦¦         19%
Jacksonville      ¦¦¦¦¦¦¦¦¦          18%
That doesn’t mean every investor should use a hard money loan in Florida. It does show why flexible financing can matter in markets where investors may be competing for distressed homes, renovation opportunities, and properties with unusual circumstances.
Local conditions matter too. A Miami condo may involve association reserves and assessments. A Cape Coral property may carry different flood and wind risks. An Orlando rental may depend heavily on realistic rent assumptions. A Tampa renovation can face a completely different resale market.
Hard money should be evaluated in the context of the actual property and local market, not Florida as a single uniform market.
Key Facts
- Hard money is generally short-term financing
- Real estate collateral plays a major role
- Faster closing can justify higher costs
- Points can substantially increase total expense
- Renovation funding may be available
- Property condition can affect financing choices
- Exit strategy is critical
- Delays can dramatically increase carrying costs
- Florida insurance should be budgeted early
- DSCR may better fit stabilized rentals
- Refinancing isn’t automatically guaranteed
- Hard money isn’t only for poor credit
People Also Ask
How much money do I need down for a hard money loan?
Requirements vary by transaction, property, current value, after-repair value, experience, and financing structure.
Why are hard money loans more expensive?
They’re generally designed for short-term, higher-risk, or more complex transactions where speed and flexibility have additional value.
What happens if I can’t repay the loan on time?
You may face extension costs, default interest, additional fees, or other consequences outlined in the financing agreement, so repayment planning is extremely important.
How Can We Help You Choose The Right Florida Financing?
We can help you determine whether hard money actually solves the problem you’re facing or whether another structure could accomplish the same goal at a lower long-term cost.
Our team can compare hard money with DSCR, Non-QM, conventional investment financing, and other available options while looking at the property condition, closing deadline, renovation plan, cash requirements, and exit strategy. You can request a free quote so we can review the numbers around your specific transaction.
You can also see what past clients have said in our customer reviews. We’re proud that The Doce Mortgage Group recently received the prestigious WalletHub Award and was recognized as one of the best mortgage brokers in several cities throughout Florida.
When you’re ready to explore whether a hard money loan in Florida makes sense for your property, you can Get Started Now, or connect with a loan officer live at 305-661-3434.