Quick Answer
Buying a triplex in Florida can be a smart investment when rental income supports the property expenses, financing fits your strategy, and you budget realistically for vacancies, insurance, maintenance, and repairs.
Buying a triplex in Florida gives you 2 very different strategies. You can live in 1 unit and rent the other 2, often called house hacking, or purchase the entire property as an investment and rent all 3 units. Both approaches can build equity and generate income, but the financing and cash requirements can be very different.
A Personal Story
I worked with a buyer who assumed a triplex automatically meant putting down a large investment-property down payment. Once I learned he planned to live in 1 unit, the conversation changed. We could evaluate owner-occupied multifamily financing and consider how rent from the other 2 units might help support the overall transaction.
My advice is to decide how you’ll occupy the property before comparing mortgage programs. Then look at realistic rents, insurance, taxes, repairs, and reserves. A triplex can be a great opportunity, but I want the numbers to work without assuming perfect tenants, zero repairs, or constant appreciation.
Is Buying A Triplex In Florida A Smart Investment?
Yes, a triplex can be a smart Florida investment when its rental income and long-term potential justify the purchase price and operating costs.
Compared with buying a single rental home, a triplex provides multiple income streams on 1 property. If 1 tenant leaves, the other occupied units may continue producing rent. For an owner-occupant, rent from 2 units may offset a meaningful portion of the monthly housing expense.
Potential advantages include:
What Makes A Triplex Attractive?
| Potential Advantage | Why It Matters |
|---|---|
| 2 rental income streams | Less reliance on 1 tenant |
| Owner-occupancy option | Expands financing possibilities |
| 3 units on 1 property | Consolidates management and maintenance |
| Equity growth | Builds ownership across the property |
| Future flexibility | Owner can later move elsewhere |
The investment side still needs careful analysis. Florida insurance premiums, flood exposure, roof condition, property taxes, repairs, utilities, and vacancies can dramatically change cash flow.
I like to treat a triplex as a small business. Gross rent is only the beginning. What matters is how much income remains after the property’s real expenses.
What Loan Options Can Finance A Florida Triplex?
FHA, conventional, VA, and specialized investment programs can potentially finance a triplex, depending heavily on whether you’ll occupy 1 unit.
If the triplex will be your primary residence, several owner-occupied options may be available.
FHA financing is particularly important because HUD permits FHA-insured financing on eligible 1-to-4-unit residential properties when occupancy and other program requirements are satisfied. FHA’s standard minimum down payment can be 3.5%.
The Doce Mortgage Group also offers Florida conventional mortgage options that can work for eligible owner-occupied multifamily purchases.
Eligible veterans and service members may also be able to use VA financing for a multi-unit property when occupancy requirements are met.
For buyers who plan to rent all 3 units, investment financing becomes more relevant. Possibilities can include conventional investment mortgages, Florida DSCR financing, and certain Non-QM programs.
Occupancy and rental income become especially important when using FHA financing for multifamily properties
How Occupancy Changes Triplex Financing
| Factor | Owner Occupies 1 Unit | All 3 Units Rented |
| Property classification | Primary residence | Investment property |
| FHA financing | Potentially available | Not available |
| VA financing | Potentially available | Not available |
| Conventional approach | Owner-occupied financing | Investment financing |
| Down payment | Can be lower | Usually higher |
| Rental income | May help qualification | Central to investment analysis |
The biggest lesson is that buying the same triplex can produce very different financing options depending on how you intend to use it.
If FHA looks like a possible fit, you can estimate the payment, mortgage insurance, taxes, and other costs using our Florida FHA Loan Calculator.
How Does FHA Financing Work For A Triplex?
FHA financing can allow you to purchase an eligible Florida triplex with as little as 3.5% down when you’ll live in 1 of the 3 units as your primary residence.
That owner-occupancy requirement is what separates this strategy from purchasing a triplex strictly as an investment. You can rent the other 2 units, and qualifying rental income may help support the mortgage.
There’s one FHA rule that triplex buyers need to understand before making an offer. Three-unit and 4-unit properties must pass FHA’s self-sufficiency test.
Under HUD’s current rules, the appraiser estimates fair market rent for all 3 units, including the unit you’ll occupy. From that amount, at least 25% is deducted for vacancies and maintenance. The remaining amount must be sufficient in relation to the property’s principal, interest, taxes, and insurance payment. HUD’s FHA Single Family Housing Policy Handbook
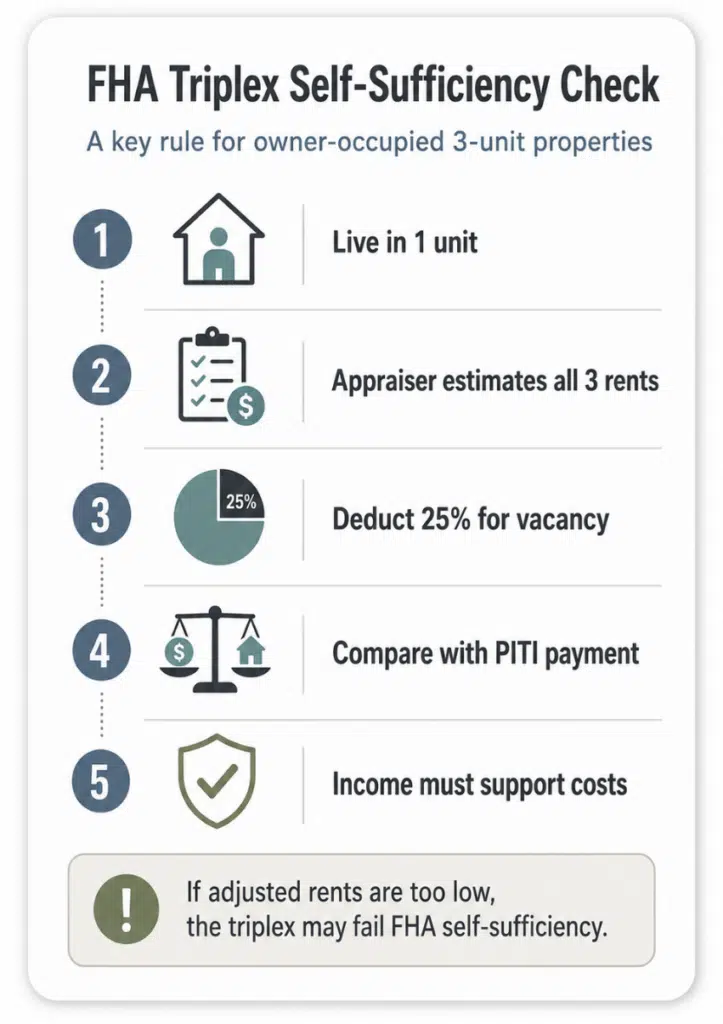
This requirement can eliminate a property that otherwise looks affordable. I’ve seen buyers get excited because their personal income easily supports the payment, only to discover that the triplex itself doesn’t generate enough estimated rent to pass the FHA calculation. That’s why I prefer checking the numbers before the buyer becomes emotionally committed to the property.
FHA also requires the property to meet applicable appraisal and condition standards. With a triplex, that means all 3 legal units matter, not just the one you plan to live in.
Can Rental Income Help You Qualify?
Yes, rental income from the other units can potentially help you qualify for a triplex mortgage.
The exact calculation depends on the financing program and your rental-property history. For conventional financing, Fannie Mae permits rental income from a 2-to-4-unit primary residence when the borrower occupies 1 unit.
When a lease or appraiser-supported market rent is used, current Fannie Mae’s rental income guidelines generally calculate qualifying rent at 75% of gross monthly rent. The other 25% accounts for expected vacancies and ongoing maintenance.
For example, suppose the 2 units you’ll rent are each expected to generate $1,800 per month.
Example Triplex Rental Income Analysis
| Rental Component | Example Amount |
|---|---|
| Unit 2 monthly rent | $1,800 |
| Unit 3 monthly rent | $1,800 |
| Combined gross rent | $3,600 |
| 75% qualifying calculation | $2,700 |
| Amount excluded for vacancy and expenses | $900 |
This example illustrates a common conventional rental-income calculation. Actual qualifying treatment can vary based on the program, documentation, occupancy, and your existing housing or property-management history.
The important point is that $3,600 of projected rent doesn’t automatically mean $3,600 gets added to your qualifying income.
Our explanation of using rental income to qualify for a mortgage goes deeper into how income from additional units may strengthen a mortgage application.
I also recommend looking at the rents conservatively from an investment standpoint. The mortgage qualification calculation and your actual cash flow are 2 different things. A unit that rents for $1,800 still has turnover, repairs, potential vacancy, and other costs.
How Much Can You Borrow On A Triplex In 2026?
Triplexes have higher mortgage limits than single-family homes, so you shouldn’t use the standard 1-unit limit when estimating how much financing may be available.
HUD’s 2026 FHA loan limits set the FHA national low-cost 3-unit limit at $837,700. The 3-unit FHA ceiling for qualifying high-cost areas is $1,933,200. Your actual FHA limit depends on the Florida county where the property is located.
Conventional limits are higher as well. FHFA’s official 2026 conforming loan limit for a 3-unit property is $1,288,800, compared with $832,750 for a 1-unit property.
2026 Three-Unit Loan Limit Benchmarks
| Financing Category | 2026 Three-Unit Limit |
| FHA national floor | $837,700 |
| FHA high-cost ceiling | $1,933,200 |
| Conventional baseline | $1,288,800 |
| Conventional high-cost maximum | $1,933,200 |
These limits are important because a triplex with a purchase price well above the normal single-family limit may still qualify for FHA or conforming financing.
When I evaluate buying a triplex in Florida, I look at the loan limit, rental income, self-sufficiency requirement, cash needed, and monthly payment together. Looking at only 1 of those numbers can give you the wrong impression about whether the purchase works.
If you have a particular triplex in mind, you can submit the property information through our secure application portal, and we can evaluate the financing structure and rental-income qualification around your actual numbers.
What If You Won’t Be Living In The Triplex?
If you plan to rent all 3 units from the beginning, the triplex will generally be treated as an investment property rather than a primary residence.
That changes your financing choices. Conventional investment financing may work for borrowers with strong income, credit, assets, and reserves. A Florida DSCR loan can be especially useful because qualification focuses heavily on whether the property’s rental income supports its required housing expense.
I like to compare more than 1 financing structure for investors. The lowest rate isn’t automatically the best choice if another option better supports cash flow, reserves, or plans to purchase additional properties.
The same principle applies when buying an investment property in Florida. Financing, rental income, expenses, and long-term goals need to work together.
What Expenses Can Make A Florida Triplex Unprofitable?
Insurance, vacancies, repairs, taxes, utilities, and major maintenance can quickly turn attractive gross rent into weak cash flow.
Florida insurance deserves particular attention. Roof age, wind exposure, flood risk, plumbing, electrical systems, and building age can affect costs. Buyers can investigate a property using FEMA flood maps, but I still recommend getting an insurance quote for the specific triplex before becoming committed to the purchase.
Also budget for tenant turnover, appliances, landscaping, pest control, property management when needed, and future expenses such as roofing and HVAC replacement.
Triplex Cash Flow Stress Test
| Scenario | What Happens | Investment Effect |
|---|---|---|
| All 3 units occupied | Full rental income | Strongest cash flow |
| 1 unit vacant | Income falls | Smaller monthly margin |
| Major repair occurs | Expenses rise | Reserves become important |
| Insurance increases | Fixed costs rise | Net cash flow falls |
| Rents increase | Income improves | Potential return improves |
I don’t want a triplex investment to depend on everything going perfectly. If the numbers only work with constant occupancy and no major repairs, the margin may be too thin.
Pros And Cons
Pros include multiple rental income streams, potential owner-occupied financing, equity growth, and managing 3 units at a single property.
Cons include more tenant management, higher maintenance exposure, vacancies, Florida insurance costs, larger repair bills, and more complicated financing.
Myths Vs Facts
Myth: A triplex always requires investment-property financing
Fact: Occupying 1 unit may make primary-residence financing available
Myth: FHA only finances single-family houses
Fact: FHA can finance eligible properties containing up to 4 units
Myth: 3 tenants automatically create positive cash flow
Fact: Insurance, taxes, vacancies, maintenance, and repairs still matter
Common Mistakes
Common mistakes include deciding on financing before determining occupancy, using unrealistic rents, overlooking FHA’s self-sufficiency test, underestimating insurance, failing to verify that all 3 units are legal, and spending too much cash at closing instead of maintaining reserves.
Key Facts
- A triplex contains 3 residential units
- Owner occupancy can change financing options
- FHA may finance qualifying owner-occupied triplexes
- Rental income may help with qualification
- FHA triplexes face a self-sufficiency test
- DSCR can work for investment triplexes
- Florida insurance can significantly affect cash flow
- Strong cash reserves can reduce investment risk
People Also Ask
Is owning a triplex profitable?
It can be when rents comfortably cover financing, taxes, insurance, vacancies, maintenance, repairs, and other operating expenses.
Is a triplex considered residential property?
Yes. A triplex generally falls within the 1-to-4-unit residential property category used by major mortgage programs.
Is a triplex better than a duplex for investment?
A triplex provides another potential rental stream, but it also creates additional management and maintenance responsibilities.
How Can We Help Finance Your Florida Triplex?
We can compare FHA, conventional, VA when eligible, DSCR, Non-QM, and other financing strategies based on whether you’ll occupy the triplex or rent all 3 units. We can also evaluate rental income, loan limits, cash requirements, and reserves before you commit to a property.
You can request a free quote and review our customer reviews to see what borrowers say about working with our team.
We’re proud that The Doce Mortgage Group recently received the prestigious WalletHub Award and was recognized as one of the best mortgage brokers in several cities throughout Florida.
If you’re considering buying a triplex in Florida, we can help you compare the numbers before you make your move, and when you’re ready, you can Get Started Now, or connect with a loan officer live at 305-661-3434.